


YIELD SHOPPER - OCTOBER 2026
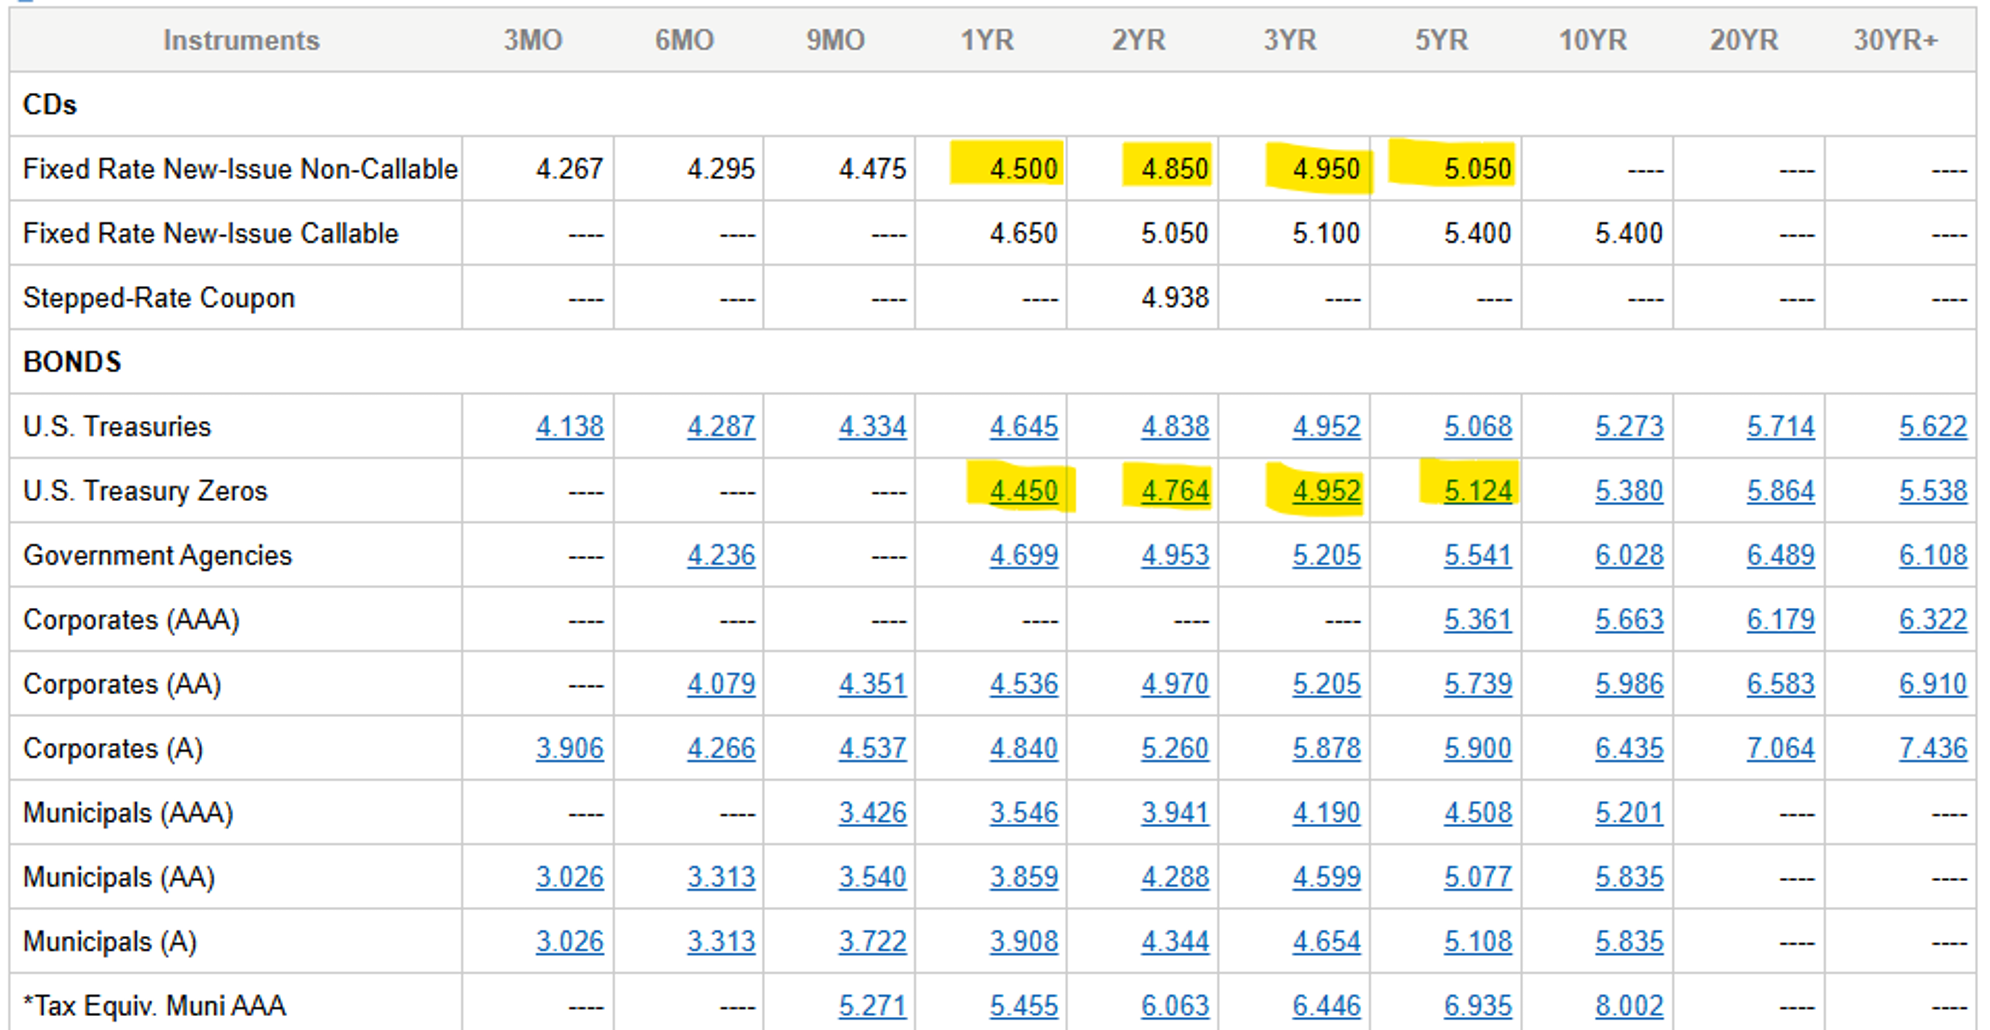
Source: Charles Schwab fixed income trading desk. 10/2/2026
*The Taxable Equivalent Municipal AAA Yield is calculated from the Municipal AAA Yield, and assumes a 35% federal tax rate. This does not reflect the effects of any state or local taxes, which, if applicable, may increase the taxable equivalent yield. For questions about calculating your individual rate, see your tax advisor. The following formula is used: Taxable Equivalent Municipal Yield = (Municipal AAA Yield) / (1.00 - 0.35).
In reviewing the yields in the table above, investors should keep in mind that the interest paid on treasury securities and certain government agencies (e.g. Federal Home Loan Bank , Federal Farm Credit Bank, and Tennessee Valley Authority) is exempt from state income tax. Interest from most (but not all) municipal bonds is exempt from federal income tax. Federally tax exempt municipal bonds issued within your residence state (or issued by U.S. territories such as Guam and Puerto Rico) are generally exempt from state income tax as well. Interest paid Certificates of Deposit, Corporate Bonds, and annuity contracts is subject to federal and state income tax. In comparing yields between these securities it may be necessary to calculate the tax-equivalent yield.
Taxable Equivalent Yield Calculator (Source: Fidelity)
All yields below are reported as to 10/2/2026
Money Market Funds
Fund Name & Symbol | 7-Day Yield | Link to Fact Sheet & Prospectus |
Schwab Prime Money Market Fund (SWVXX) | 3.71%% | |
Schwab U.S. Treasury Money Fund (SNSXX) | 3.52% | |
Schwab U.S. Treasury Money Fund (Ultra Shares) SUTXX | 3.67% | |
Fidelity Prime Money Market Fund (SPRXX) | 3.56% | |
Fidelity Treasury Only Money Fund (FDLXX) | 3.48% | |
Vanguard Cash Reserves Fed MMF (VMRXX) | 3.80% | |
Vanguard Treasury Money Fund (VUSXX) | 3.80% |
Cash & Cash-Like ETFs
Issuer | APY | Link to Fact Sheet & Prospectus |
Vanguard 0-3 Month T-Bill ETF (VBIL) | 3.63% | |
iShares 0-3 Month Treasury ETF (SGOV) | 3.69% | |
SPDR 1-3 Month T-Bill ETF (BIL) | 4.01% | |
Schwab Short Term U.S. Treas ETF (SCHO) | 4.64% |
High Yield Savings Account Rates (Source: Bankrate.com and NerdWallet.com)
Bank | APY |
CIT Bank | 4.25% |
Happen Bank | 4.20% |
VIO Bank | 4.01% |
Bread Financial | 4.00% |
Sample Online Bank CD Rates (Source: Bankrate.com)
Bank | 6 month | 12 month | 2 Year | 5 year |
E*Trade | 4.20% |
|
|
|
E*Trade |
| 4.40% |
|
|
Happen Bank |
|
| 4.40% |
|
Synchrony Bank |
|
|
| 4.50% |
Readers of my commentary know that I do not ever recommend bond mutual funds or ETFs (aside from money market ETFs). I have written many articles on this topic, which are included below. This position is also shared by retirement researcher and financial planning industry thought leader Wade Pfau, PhD, CFA. Links to Wade’s commentary on this topic are as follows
3 Ways to Incorporate Bonds Into Your Retirement Strategy (Retirement Researcher)
Why Bond Funds Don’t Belong in Retirement Portfolios (Wade Pfau, Advisor Perspectives)
Laddering with Individual Bonds (Retirement Researcher)
JOHN ROBINSON’S RUNNING COMMENTARY ON FIXED INCOME INVESTMENTS FROM THE FPH BLOG
Laddering with Treasury STRIPS (10/2/2026)
How Not to Invest in Bonds (8/31/2026)
Short-Term Laddered Bond ETFs vs. Short Term Bond Funds (9/25/2025)
Cash ETFs: The New “New Thing” in the Search for Yield and Safety? (9/25/2025)
Government Money Market Funds Are Not All The Same (2/9/2025)
Why I Always Say “Friends Don’t Let Friends Buy Bond Funds (4/1/2025)
Not So Hot TIPS (11/1/2024)
Keeping Score – A Running Record of My Interest Rate and Fixed Income Guidance Since 2020 (6/5/2024)
Where to Fish for the Best Fixed Income Yields Today (3/4/2024)
Interest Rates on CDs Plummeted in November. How to Invest Now (12/3/2023)
How to Invest When the Yield Curve is Inverted (9/8/2023)
It's Time to Start Laddering Certificates of Deposit Again (5/21/2023)
Is Your Cash Working as Hard as it Should Be? 2/16/2023
How to Invest in Bonds and CDs Now that Interest Rates Have Risen 12/10/2022
Where to Stash Cash Now 9/29/2022
I was Right About Interest Rates 9/29/2022
The Time to Buy Series I Savings Bonds is NOW! 4/18/2022
Why Friends Don’t Let Friends Buy Bond Funds (3/1/2022)
Saying that the Bull Market in Bonds is Over is NOT Market Timing 12/10/2021
Negative Returns Ain’t Much of a Living (8/9/2021)
Looking for Yield in All the Wrong Places (5/25/2021)
John H. Robinson is the founder of Financial Planning Hawaii and Fee-Only Planning Hawaii and a co-founder of retirement simulation software, Nest Egg Guru.
Financial Planning Hawaii is an SEC-Registered Investment Adviser (RIA). Registration as an investment adviser does not imply any level of skill or training. For verification of Financial Planning Hawaii's regulatory status, all website visitors are encouraged to visit the SEC Investor Advisor Public Disclosure website. The site allows you to search by firm name and by adviser name. It provides detailed information about the firm's business model and each investment adviser representative's professional experience, educational background, and disclosure history.
Financial Planning Hawaii's 2026 SEC Form ADV | Financial Planning Hawaii's 2026 Customer Relationship Summary