


Yield Shopper - NOVEMBER 2026
YIELD SHOPPER By Financial Planning Hawaii
Your Go-To Source for Interest Rates on CDs, Bonds, and other fixed income investments
Yield Shopper is a service for helping Financial Planning Hawaii Clients keep abreast of current yields on money market funds, high yields savings accounts, CDs, treasuries, agency securities, municipal bonds, corporate bonds, and other popular fixed income investments.
JR’s Two Cents on the Fixed Income Marketspace
Yields on bonds have fallen a little over the past couple of weeks. At their peak at the beginning of November, we could get 5%+ for 2 years and longer on CDs. At this writing (11/13/2027), the best two-year rate is around 4.9%, which is still a good bit higher than the beginning of the year.
My thesis is unchanged - I believe it is more likely than not that rates will rise further from here, and there is a better than average chance that the $40 trillion+ national debt will foster a secular rising rate environment as investors demand higher interest rates on U.S. treasuries as compensation for the additional credit risk they are taking. Persistent inflation will fan the flames.
At this time, I am comfortable extending maturities out as far as two years. If rates tick back up to 5% at three and four years, I support extending CD and treasury ladders out as far as 5 years. Consistent with our dynamic ladder strategy, we should still weight the ladder to the shorter maturities.
HERE IS A SNAPSHOT OF FIXED INCOME RATES AS OF THE FIRST WEEK OF SEPTEMBER 2026
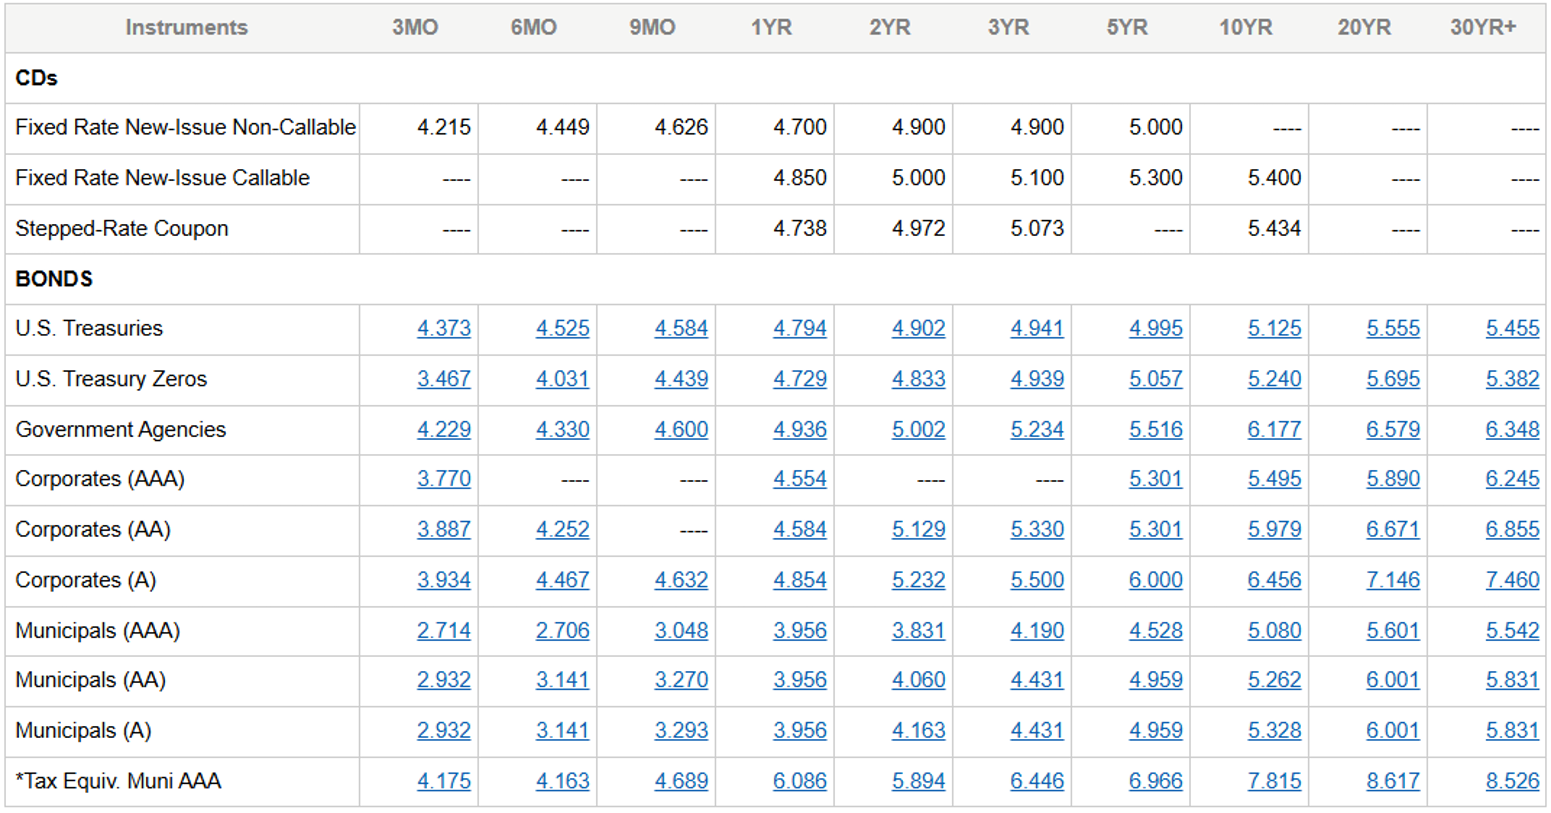
Source: Charles Schwab fixed income trading desk. 11/13/2026
*The Taxable Equivalent Municipal AAA Yield is calculated from the Municipal AAA Yield, and assumes a 35% federal tax rate. This does not reflect the effects of any state or local taxes, which, if applicable, may increase the taxable equivalent yield. For questions about calculating your individual rate, see your tax advisor. The following formula is used: Taxable Equivalent Municipal Yield = (Municipal AAA Yield) / (1.00 - 0.35).
In reviewing the yields in the table above, investors should keep in mind that the interest paid on treasury securities and certain government agencies (e.g. Federal Home Loan Bank , Federal Farm Credit Bank, and Tennessee Valley Authority) is exempt from state income tax. Interest from most (but not all) municipal bonds is exempt from federal income tax. Federally tax exempt municipal bonds issued within your residence state (or issued by U.S. territories such as Guam and Puerto Rico) are generally exempt from state income tax as well. Interest paid Certificates of Deposit, Corporate Bonds, and annuity contracts is subject to federal and state income tax. In comparing yields between these securities it may be necessary to calculate the tax-equivalent yield.
Taxable Equivalent Yield Calculator (Source: Fidelity)
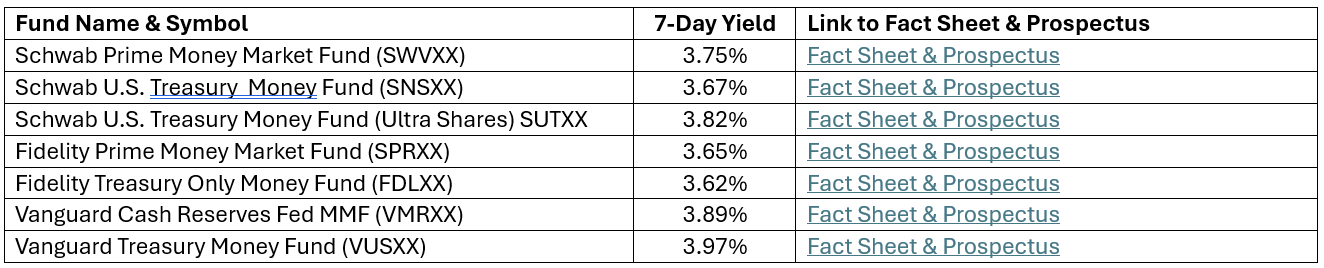
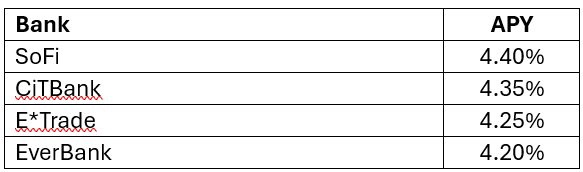
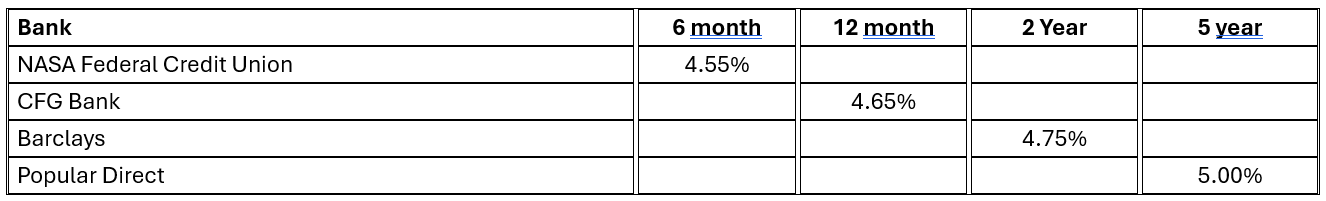
All yields below are reported as to 8/28/2026
Money Market Funds
High Yield Savings Account Rates (Source: Bankrate.com and NerdWallet.com)
Sample Online Bank CD Rates (Source: Bankrate.com)
Readers of my commentary know that I do not ever recommend bond mutual funds or ETFs (aside from money market ETFs). I have written many articles on this topic, which are included below. This position is also shared by retirement researcher and financial planning industry thought leader Wade Pfau, PhD, CFA. Links to Wade’s commentary on this topic are as follows:
3 Ways to Incorporate Bonds Into Your Retirement Strategy (Retirement Researcher)
Why Bond Funds Don’t Belong in Retirement Portfolios (Wade Pfau, Advisor Perspectives)
Laddering with Individual Bonds (Retirement Researcher)
Do Bond Investors Get Rewarded for Taking Duration Risk? (Part 1) (McQuarrie & Bernstein, Advisor Perspectives)
JOHN ROBINSON’S RECENT COMMENTARY ON FIXED INCOME INVESTMENTS FROM THE FPH BLOG
Not Bond Laddering. DYNAMIC Bond Laddering! (10/11/2026)
Why We Prefer Not to Have Losses to Harvest (10/11/2026)
Laddering with Treasury STRIPS (10/20/2026)
Bond Market Wisdom From Hawaii’s Nest Egg Guru (10/4/2026)
How Not to Invest in Bonds (8/31/2026)
Short-Term Laddered Bond ETFs vs. Short Term Bond Funds (9/25/2025)
Cash ETFs: The New “New Thing” in the Search for Yield and Safety? (9/25/2025)
Government Money Market Funds Are Not All The Same (2/9/2025)
Why I Always Say “Friends Don’t Let Friends Buy Bond Funds (4/1/2025)
Not So Hot TIPS (11/1/2024)
Keeping Score – A Running Record of My Interest Rate and Fixed Income Guidance Since 2020 (6/5/2024)
Where to Fish for the Best Fixed Income Yields Today (3/4/2024)
Interest Rates on CDs Plummeted in November. How to Invest Now (12/3/2023)
How to Invest When the Yield Curve is Inverted (9/8/2023)
It's Time to Start Laddering Certificates of Deposit Again (5/21/2023)
Is Your Cash Working as Hard as it Should Be? 2/16/2023
How to Invest in Bonds and CDs Now that Interest Rates Have Risen 12/10/2022
Where to Stash Cash Now 9/29/2022
I was Right About Interest Rates 9/29/2022
The Time to Buy Series I Savings Bonds is NOW! 4/18/2022
Why Friends Don’t Let Friends Buy Bond Funds (3/1/2022)
Saying that the Bull Market in Bonds is Over is NOT Market Timing 12/10/2021
Negative Returns Ain’t Much of a Living (8/9/2021)
Looking for Yield in All the Wrong Places (5/25/2021)
John H. Robinson is the founder of Financial Planning Hawaii and Fee-Only Planning Hawaii and a co-founder of retirement simulation software, Nest Egg Guru.
Financial Planning Hawaii is an SEC-Registered Investment Adviser (RIA). Registration as an investment adviser does not imply any level of skill or training. For verification of Financial Planning Hawaii's regulatory status, all website visitors are encouraged to visit the SEC Investor Advisor Public Disclosure website. The site allows you to search by firm name and by adviser name. It provides detailed information about the firm's business model and each investment adviser representative's professional experience, educational background, and disclosure history.
Financial Planning Hawaii's 2026 SEC Form ADV | Financial Planning Hawaii's 2026 Customer Relationship Summary